*This is a collaborative guest post.
Juggling family life and finances can often feel like trying to fill a leaky bucket. You pour your effort into careful meal planning and budgeting, only to find the money disappearing faster than a packet of biscuits left on the counter. It’s a common story for households everywhere, where the weekly food shop can feel like the biggest battleground for your bank balance. Getting a handle on your grocery spending isn’t just about saving a few quid; it’s about building financial confidence that supports your family’s well-being.
Budgeting for Groceries and Meals
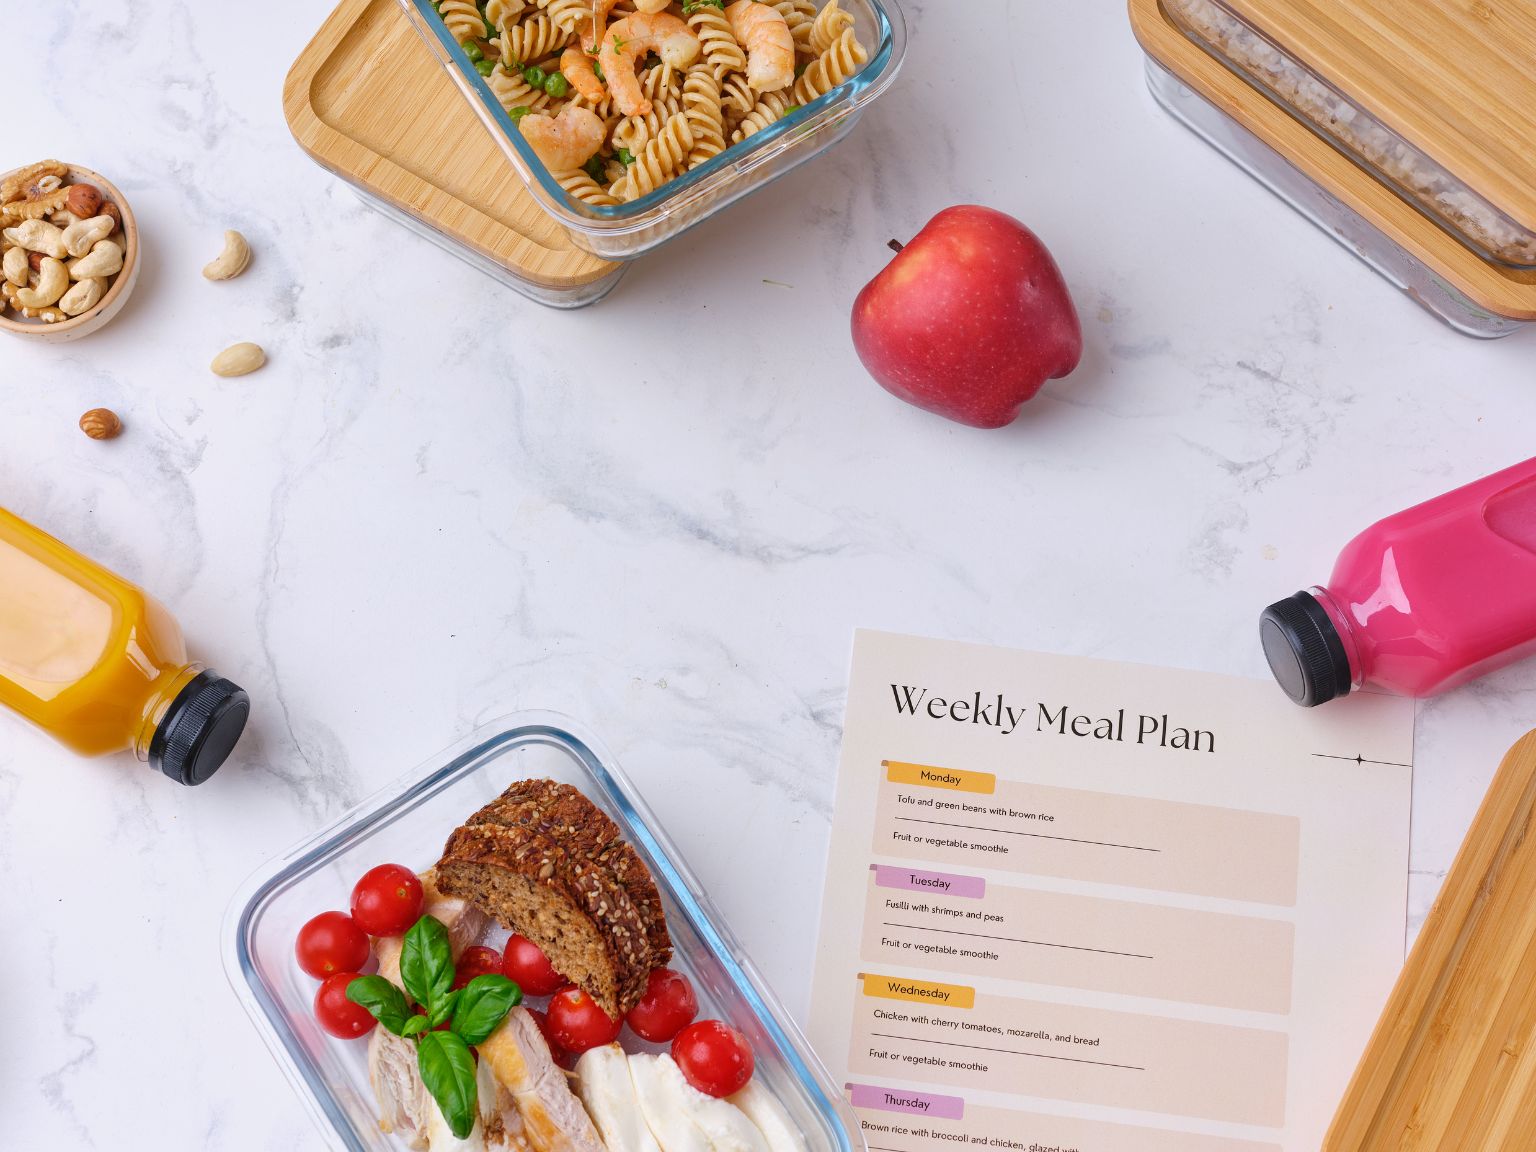
Saving money on food starts with a solid plan. Walking into a supermarket without a list is an open invitation for impulse buys and overspending. The trick is to move from reactive shopping to proactive planning. Start by setting aside a little time each week to plan out your family’s meals. This doesn’t have to be a rigid schedule, but a rough guide that makes sure you buy what you need and use what you buy.
Once you have a meal plan, create a detailed shopping list. Sticking to this list is your best defence against temptation. For more help, you can find great resources online, like this 8-step grocery method that breaks down the process into manageable steps. Many families also find success by combining different strategies. Exploring various budgeting and meal planning tips can help you discover what works best for your household’s routine and tastes. Think about these habits:
- Shop your own pantry first: Before you write your list, check what you already have. You might be surprised by the meals you can create with existing ingredients.
- Embrace batch cooking: Cooking larger portions of meals like chilli, bolognese, or curry and freezing them for later saves both time and money.
- Love your leftovers: Plan for a ‘leftover night’ or turn cooked meat and vegetables into new meals like pies or stir-fries.
Unexpected Costs of Family Life
Even the most organised household budget can be thrown off course by life’s little surprises. Just when you think you’ve got your grocery spending under control, the washing machine gives up, a surprise school trip is announced, or your child has a sudden growth spurt that makes their entire wardrobe useless overnight. These unexpected expenses are a normal part of family life, but they can cause significant financial stress if you’re not prepared.
This is why having a financial safety net is so important. An emergency fund is money put aside specifically for these unforeseen events. It’s the buffer that stops a broken-down car from becoming a full-blown financial crisis. The challenge for many people is knowing how much they actually need to save. The amount varies depending on your income, monthly outgoings, and family situation. A good first step is to get a clear picture of your target by using a tool like an emergency fund calculator. This can help you set a realistic goal and break it down into achievable steps, turning the vague idea of ‘saving for a rainy day’ into a concrete, manageable plan.
Why Your Savings Number Matters
Knowing your savings target is powerful. It turns saving from a chore into a goal-oriented mission. When you have a specific number to aim for, whether it’s three months of essential living costs or the price of a new boiler, every pound you set aside feels more meaningful. This number isn’t just about covering emergencies; it’s about buying yourself options and reducing the background hum of financial anxiety that so many families experience.
Having that financial cushion changes how you approach problems. Instead of panicking when the car fails its MOT, you can focus on finding the best solution without the added stress of figuring out how to pay for it. This sense of security has a ripple effect on your entire family’s well-being. When parents are less stressed about money, they have more mental and emotional energy to devote to their children and each other. It creates a more stable and positive home environment. The savings number represents more than just money in the bank; it represents resilience, stability, and the freedom to handle life’s ups and downs with confidence.
Stress-Free Family Finance Habits
Building long-term financial health means creating simple, sustainable habits that work for your family. It’s not about deprivation or complicated spreadsheets but about fitting smart money management into your daily life. The goal is to make these practices so routine that they happen almost automatically, freeing up your brainpower for more important things, like planning a weekend adventure with the kids.
Start by scheduling a regular, low-pressure ‘money check-in’ with your partner. This could be a 15-minute chat over a cup of tea every fortnight to review spending, check progress towards goals, and discuss any upcoming expenses. Keeping the conversation open and collaborative prevents financial stress from building up. Another effective habit is automation. Set up a standing order to transfer a fixed amount of money into your savings account on payday. By paying yourself first, you prioritise your financial goals without having to rely on willpower. Finally, involve your children in age-appropriate ways. Giving them pocket money and the responsibility to save for something they want is a brilliant way to teach them valuable financial lessons from an early age.
Ultimately, mastering your family’s finances is a journey of small, consistent actions. Combining smart meal planning with a clear strategy for savings helps you build a strong financial foundation that supports your family through every stage of life.